SME Phase 1, one last call and a long-lasting impact in almost 4000 start-ups
For some time at Viromii we have been developing a tool that facilitates technology transfer activities by helping experts identify the right companies and people to approach, in order to advance in its development, we just applied for the SME phase 1 instrument. The deadline to submit the application was last week and there is one last call for SME phase 1 closing in September, after then, SME phase 1 will no longer exist. Today we want to share some interesting numbers about this funding instrument and its impact.
Horizon 2020, until this day the biggest research and innovation funding program launched by the EU with €80 billion of funding, is coming to an end; the 1st of January 2021 the new program, Horizon Europe, will be launched with a budget of €100 billion. Many changes are coming with the implementation of Horizon Europe, especially regarding SME instruments; phase 2 will continue with minor changes, such as the possibility of applying for equity funding from the EU, yes, there will be companies who will count the EU among their shareholders. By contrary, SME phase 1 instrument will not exist under Horizon Europe and as the transition has already started, SME phase 1 will have its very last call deadline by September the 5th of 2019.
SME phase 1 has been alive from 2014 with the objective of funding innovative European SMEs to carry out feasibility assessments, with a maximum amount of 50.000€ per project. From 2014 a total of 183,5 Million of € have been allocated, benefiting 3837 small and medium enterprises. If we take a look at country level, Spain is the clear leader in terms of granted applications, a total of 690 Spanish SMEs have benefited from this instrument, following Spain we have Italy, with 557 granted applications, and the UK, with 354 beneficiaries, Sweden is in the seventh position, with 170 companies who have gotten the grant.

Regarding topics, most money has been allocated to projects focused on ICT, 33 million €, construction & transport networks and energy account for around 20 million € each, followed by health with 16 million €. Surprisingly, even though Fintech is one of the hottest topics in the start-up scene, projects around finance have only received 1 million €, probably because most of Fintech companies have applied in the ICT category.
Finally, we did a quick comparison between Spain and Sweden. In terms of percentage of money per topic, both are quite similar. Agriculture and food are important sectors in Spain, which can be seen by the percentage of projects that Spain has in these sectors. By contrast, Sweden is one of the most innovative countries in Europe in the healthcare and biotechnology sectors, fact that is also shown in the comparison. These numbers are not a surprise and represent the reality of both countries.

With this post, we just wanted to show how SME phase 1 instrument has helped a lot of innovative small firms as a first step to bring their innovations to the market. From Viromii we hope that Horizon Europe continues supporting early stage SMEs as Horizon 2020 has done, for this we need a new SME phase 1 instrument, but sadly looks like it won’t happen.
Sources:
https://sme.easme-web.eu/
https://ec.europa.eu/info/designing-next-research-and-innovation-framework-programme/what-shapes-next-framework-programme_en
Which are the most important performance parameters in ventures and start-ups?
We, at Viromii. have asked this question to many actors within the european startup ecosystem, and found interesting insights that are worth sharing with you. Performance parameters are usually variable depending on the industry or type of venture, however, there are always a set of underlying invariable parameters that will indicate better or worse performance.
According to a set of six international incubators and accelerators from different countries, the key venture performance parameters were the following:
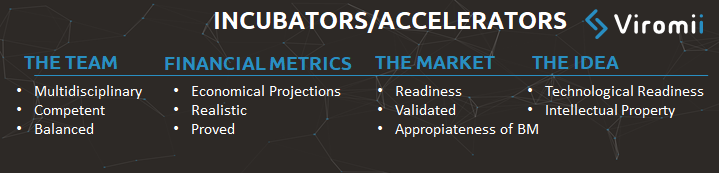
As we can see, incubators and venture accelerators had a very holistic approach towards venture analysis. From here, it can be highlighted the part of financial metrics, where these institutions wanted an actual economic proof that the business was reliable. This can be due to the fact that incubators and accelerators usually invest to a certain extent in their hosted companies, looking for a ROI and also for a high survival and success ratio that will be good publicity for their business, and increase their reputation.
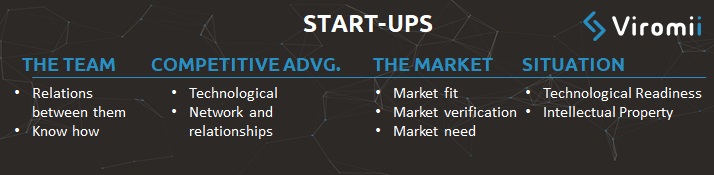
If we ask the same question to startups, we see many similarities but small changes in the perception of what is important for them. In the team, for example, what they value the most is the relations between the team itself and if they are qualified for the job at the startup. This is rather understandable, as they are the ones that have to deal with the team on an everyday basis. In what incubators and accelerators perceive as the idea, startups perceive their competitive advantage, and here is where the founders add the network.The market side is, on the other hand, very straightforward and similar for both actors. Furthermore, something interesting is how startups separate the situation as the timing for setting up the company and location where you set up the firm, from the market, which, in our opinion are very related.
According to investors, they did not separated these factors as the other actors did, but ranked them in a more piramidal way. In this system, the basis would be built by a capable team flexible enough to accept structural and organizational changes. That team should come with a robust idea built over a strong technological basis. If these two parameters are on place, then the market should be validated, scouted, and ready for the acceptance of this technology. Finally, after having all these variables settled, it comes the intellectual property to correctly control the capitalization and secure the position of the innovation in the market.
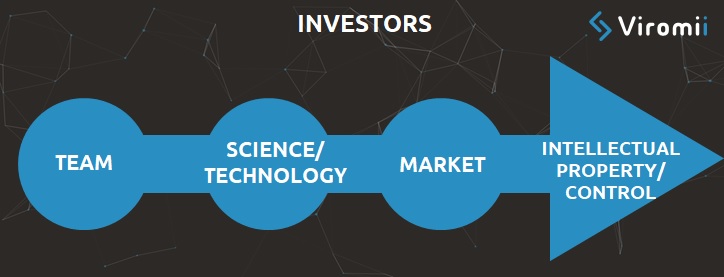
In conclusion, although there exist similarities between start-ups, incubators, and investors, in how they analyze and understand venture performance parameters, the perception is what varies. From this, we can extract that these performance parameters are heavily reliant on the business model of each specific actor, where for a start-up is usually financial and market growth, while for an incubator might be survival ratio and publicity, and for an investor looks to be how sound is the business in a more holistic perspective.